Sumio: Net Worth Tracker

Screenshots
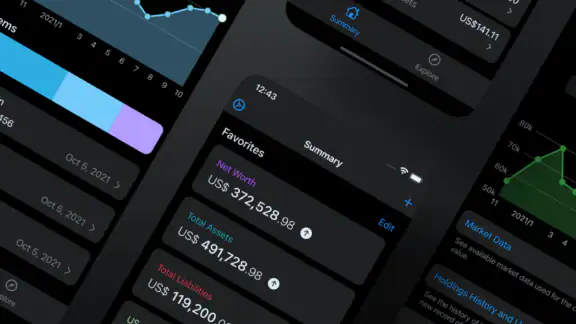
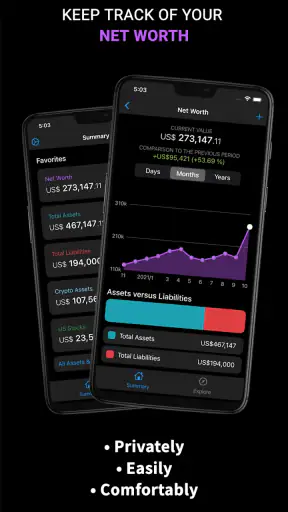
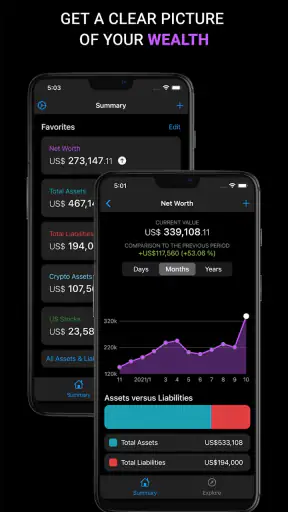
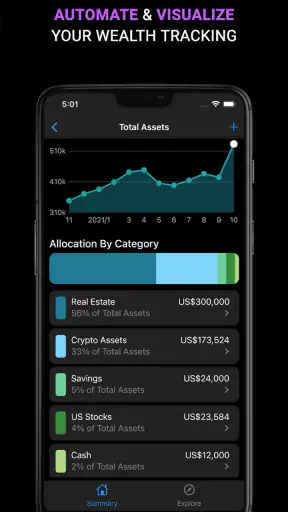
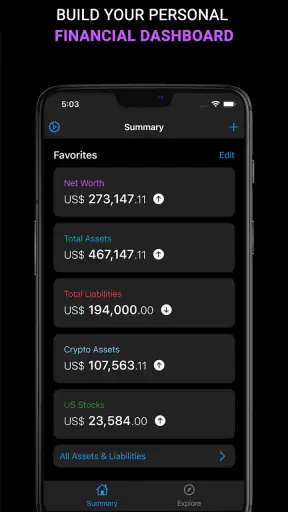
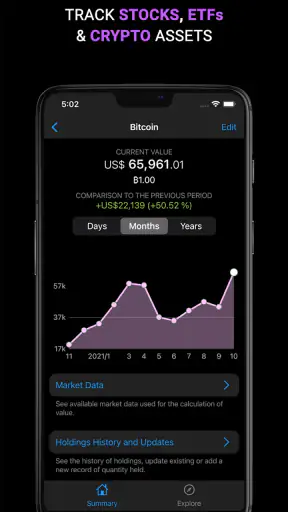
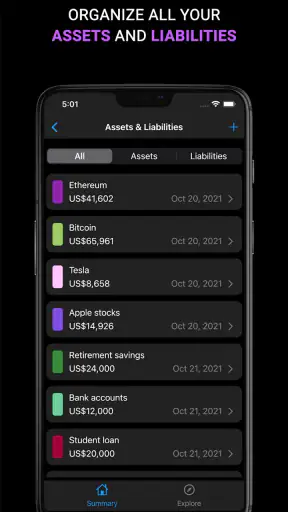
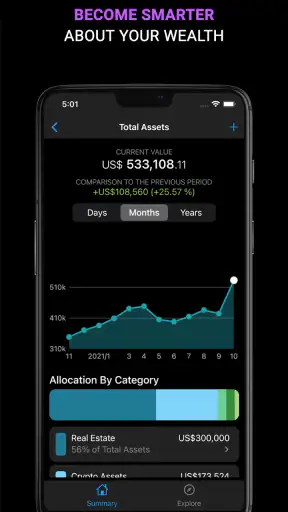
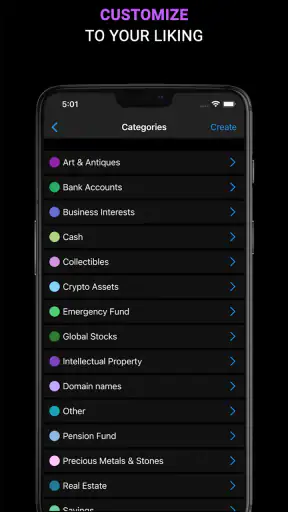
Details
- Rating
- 5.00 reviews
- Version
- 1.9.18
- Developer
- Fiduciary
Analysis by Norviv
I approached Sumio: Net Worth Tracker as a simple question: can it make my complete financial position easier to understand than a collection of banking, brokerage, and notes apps? Its central idea is straightforward—bring net worth, investments, stocks, funds, and other assets into one view—but the useful part is not the total itself. The real benefit is seeing how separate financial decisions change the same overall picture.
That makes this free finance app from Fiduciary more interesting than a basic balance calculator. I would not treat it as a replacement for a bank or investment platform. Instead, I see it as a personal overview tool: a place to organize the pieces of my financial life and check whether my direction still matches my plans. The app is available for everyone, supports Android from version seven onward, and includes optional in-app purchases ranging from a few dollars to several dozen dollars per item.
Why tracking net worth in one place changes the way I look at money
Most people know the balance of their main account, but that number rarely represents their actual financial position. Savings, retirement holdings, shares, funds, property, vehicles, debt, and cash can all sit in different places. I found that the strongest idea behind Sumio is its attempt to turn those scattered figures into one understandable picture.
That single view changes the question from “How much is in my account today?” to “Am I building wealth over time?” Those are very different questions. A checking balance can look healthy just before a large bill, while an investment account can fluctuate without changing a long-term plan. Looking at net worth encourages me to consider both sides: what I own and what I owe.
The app’s focus on investment portfolios, stocks, funds, and assets also gives the overview more detail than a manually written total. I can think about the composition of my finances instead of watching one headline figure. For example, a growing total may be less reassuring if it depends too heavily on one type of holding. Conversely, a quiet month in a brokerage account may matter less when savings and other assets are progressing steadily.
The most useful capability is not recording a number; it is creating a repeatable financial snapshot. If I update it consistently, I can compare my position from one check-in to the next and notice patterns that are easy to miss when I open accounts separately. That makes the app especially relevant to people who want awareness without constantly monitoring markets.
What I would use it for first
My first practical use would be a monthly money review. I would choose a calm day, check current balances, update the relevant holdings and liabilities, and then look at the overall result rather than reacting to a single account. This creates a useful pause between everyday spending and long-term planning.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would also use it before making a major decision. If I were considering a move, a large purchase, or a change in investment contributions, a consolidated view could reveal whether the decision affects liquidity, debt, or overall progress. The app cannot decide for me, but it can make the consequences easier to see.
Another less obvious use is separating emotional market noise from genuine financial change. If a stock or fund moves sharply, I can look at the broader portfolio and total net worth before assuming that the whole plan is failing. That habit is valuable because people often overreact to the most visible account rather than the complete picture.
How the tracking experience works in everyday use
I would approach the app as a personal ledger and dashboard rather than as an always-on financial command center. The quality of the result depends on how carefully I enter and maintain the information. A total is only meaningful when the assets and liabilities behind it are reasonably current.
That introduces an important trade-off. Manual attention can feel slower than an app that automatically connects to every financial institution, but it can also make me more aware of what is being counted. I am less likely to forget an old investment, overlook a liability, or assume that a bank balance represents my entire situation.
For a clean setup, I would begin with broad categories rather than trying to perfect every detail immediately. I would record the main cash accounts, investment holdings, funds, significant assets, and debts first. After the initial picture looks sensible, I would refine the entries that have the biggest effect on the total. This is more practical than spending an hour making small estimates precise while missing a major account.
For investments, I would review the difference between the current market value and the amount I originally contributed. That distinction helps prevent a common mistake: treating a temporary price increase as spendable money. The app’s value here is organizational, but the interpretation still belongs to me.
I would also decide in advance how often to update each kind of information. Cash balances may deserve more frequent attention, while a long-term asset may only need a periodic estimate. Updating everything every day could turn a helpful overview into a chore. A consistent schedule is more useful than constant checking.
A realistic monthly scenario
Imagine I receive my salary, pay regular bills, add money to a fund, and move part of my cash into savings. If I only check my current account, the month may look disappointing because several transfers reduced the visible balance. In a net-worth view, those transfers may simply show money moving between categories rather than disappearing.
At the same time, the overview could expose a different issue. Perhaps my investments increased, but my cash reserve fell too far. The total might still be positive, yet my short-term safety has weakened. That is an important distinction: net worth measures the broader position, while liquidity determines how comfortably I can handle an unexpected expense.
This is where I think Sumio can improve financial conversations. Instead of saying “I have less money this month,” I can ask whether I have less cash, fewer assets, more debt, or simply a different allocation. Those details lead to better decisions than a single account balance.
Where it fits beside ordinary alternatives
A spreadsheet offers more flexibility. I can build custom formulas, add notes, create charts, and design exactly the categories I want. For someone who enjoys financial modeling, a spreadsheet may remain the stronger option. Its weakness is maintenance: it is easy to abandon, duplicate entries, or lose track of which figures are current.
Banking apps are better for immediate transactions and account-specific activity. They show what happened in one institution, but they are usually not designed around a complete personal balance sheet. Brokerage apps are more suitable for orders, market information, and portfolio activity, while Sumio’s appeal is the wider view across investments and other assets.
Dedicated budgeting tools often focus on income, spending categories, and monthly limits. That is useful when the main problem is controlling expenses. Sumio is better suited to the separate question of accumulation: how daily choices, saving, investing, and ownership affect the value of everything together. Someone who needs detailed transaction categorization may prefer a budgeting specialist, while someone who wants a wealth snapshot may find this approach less cluttered.
I also see a difference from simply writing a net-worth number in a notes app. A note can preserve a total, but it does not naturally encourage me to think about the underlying groups of assets and investments. The dedicated structure makes the review more repeatable, even if it requires me to keep the entries updated.
The trade-offs I noticed before relying on it
The first limitation is that a consolidated figure can create false confidence. A rising total does not automatically mean I am financially secure. An asset may be difficult to sell, a market value may change quickly, or a large portion of the total may be tied up for the long term. I would use the number as a planning signal, not as permission to spend.
The second issue is consistency. If I update one account but forget another, the trend becomes misleading. This matters particularly when investments, funds, and other assets change at different speeds. I would record the date of each review and avoid comparing a fully updated snapshot with one that is clearly incomplete.
The third trade-off concerns detail versus simplicity. A broad asset total is quick to maintain, but it hides composition. Recording every holding may produce a clearer portfolio picture, yet it takes more effort. I would only add detail that helps me make a decision. If a small item never changes my plans, tracking it precisely may not be worth the time.
The app’s average rating is 3.8 from roughly eighty ratings, with around ten thousand installs. I read that as a sign of a modest, still-developing user base rather than overwhelming proof that it suits everyone. I would try it with a manageable set of accounts first and judge whether the update routine feels sustainable.
The current version is 1.9.18, and the app is free to install. Optional purchases are available, so I would check which parts of the experience require payment before building my entire workflow around them. That is not necessarily a problem, but it is worth understanding early: a free starting point does not always mean every advanced convenience is included without cost.
Privacy-minded habits and sensible expectations
Because this is a finance app, I would be careful about how I use it. I would avoid treating any personal finance tracker as a substitute for secure account access, official statements, or professional advice. I would also keep my entries understandable enough that I could verify them against the original institution when something looks wrong.
For me, the safest workflow would be to use the app for summarized values and planning, then confirm important figures in the relevant bank or investment account. Before tax decisions, loan applications, or major investment changes, I would rely on official records and qualified advice rather than a personal dashboard alone.
There is also a psychological consideration. Seeing a net-worth total move down because of market volatility can be uncomfortable, even when the long-term plan has not changed. I would avoid opening the app repeatedly during turbulent periods. A scheduled review reduces the temptation to make an emotional decision based on a short-term movement.
Who gets the most value from this approach
I think the strongest audience is someone with more than one financial account who wants a broad, understandable overview. That could include a person building savings while investing, a household managing several asset types, or an early investor who wants to learn how portfolio changes affect total wealth.
It may also help people who have outgrown a single bank balance but do not want the complexity of a full financial planning system. The app gives me a middle ground between a blank spreadsheet and a collection of specialized services. Its usefulness grows when I have several categories to compare, but the process remains understandable enough for a personal routine.
A beginner can benefit if they treat the app as an educational record rather than a source of investment instructions. Updating assets and liabilities teaches the difference between ownership, liquidity, growth, and debt. That is a more valuable lesson than watching a single stock quote.
I would be less enthusiastic for someone whose only need is strict expense budgeting. If the main goal is tracking every purchase, setting spending limits, or analyzing merchant categories, a dedicated budgeting app is likely a better match. I would also hesitate to recommend it to someone unwilling to maintain figures manually or review whether the entries remain current.
Likewise, active traders may want specialist market tools with deeper real-time analysis and execution features. Sumio’s strength is the personal overview, not replacing the platform where trades are researched and placed. The same applies to people who need formal accounting, tax reporting, or business bookkeeping; a net-worth tracker is not designed to carry those responsibilities.
My practical routine for getting better results
I would keep the first setup deliberately simple, then use three checks during each review. First, I would ask whether every major asset and liability is represented. Second, I would check whether cash and investments are balanced in a way that fits my near-term needs. Third, I would compare the change with real actions, such as saving, investing, paying debt, or making a large purchase.
I would avoid celebrating a higher total without asking what caused it. Was the change the result of new contributions, market movement, debt reduction, or an updated estimate? That question turns the app from a passive number display into a decision tool.
I would also keep a short note outside the total about unusual changes, such as a one-time payment or a transfer between accounts. Without context, a later review can make a normal event look like a trend. Even a simple explanation helps me interpret the history more honestly.
Finally, I would choose a review interval I can maintain for several months. The best financial tracker is not the one I inspect once with great enthusiasm; it is the one I can return to without friction. If Sumio makes that habit easier than my current spreadsheet or scattered notes, it has earned a place in my routine.
My final view after weighing the idea
Sumio: Net Worth Tracker is appealing because it focuses on a financial question that ordinary account apps often leave unanswered: how do all my assets, investments, funds, stocks, and liabilities fit together? I like that its purpose is broader than checking a balance, yet more approachable than building a complicated personal finance system from scratch.
Its success depends on honest maintenance and sensible interpretation. It will not remove the need to verify figures, understand risk, manage spending, or seek advice when a decision is serious. It can also feel limited if I expect a full budgeting platform, a trading terminal, or automatic professional analysis.
For my own use, I would recommend trying it as a monthly net-worth checkpoint. Start with the major categories, keep the entries consistent, and use the result to ask better questions rather than chase a constantly rising number. If you want a calmer, wider view of your finances instead of another app focused on one account, this is the role Sumio can fill well.
Frequently Asked Questions
01What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is designed to help you monitor your overall financial position in one place. You can record assets such as bank balances, investments, property, and valuables, then compare them with debts and other liabilities. The app focuses on net worth tracking rather than replacing a full banking or accounting service, making it useful for reviewing long-term financial progress.
02Do I need to connect my bank accounts to use Sumio?
No, you can generally use Sumio without linking a bank account. Manual entry allows you to add balances, assets, debts, and other financial information yourself, which may appeal to users who prefer greater privacy or whose institutions are unsupported. If account connections are available in your region, you should still review the permissions, supported providers, and update behavior before enabling synchronization.
03What types of assets and liabilities can I track in Sumio?
Sumio is intended to cover more than ordinary checking and savings accounts. Depending on your setup, you can organize items such as cash, investments, real estate, vehicles, digital assets, loans, credit-card balances, and other debts. Categorizing these entries helps the app calculate a clearer net-worth figure and makes it easier to see which areas are improving or reducing your total.
04Is Sumio: Net Worth Tracker safe for managing personal financial information?
Because a net-worth tracker can contain sensitive information, privacy and security should be considered before entering detailed data. Avoid sharing your login credentials and review the app’s privacy policy, data-storage practices, subscription terms, and any permissions requested. Manual tracking can limit connection-related exposure, but you should still use a strong password and keep your device and operating system protected.
05Is Sumio free, and does it offer premium features?
Sumio may provide a free way to begin tracking your finances, while some advanced tools can require a subscription or in-app purchase. Premium availability, pricing, trial periods, and included features may differ by platform, country, or current developer offering. Before downloading or starting a trial, check the App Store or Google Play listing carefully, especially the renewal terms and cancellation instructions.


